
We financed a multi-trillion-dollar digital revolution on top of an industrial base that can barely secure a copper wire. Here is why the AI boom is about to hit a physical wall
The Easy Story, then the Harder One
Artificial intelligence is getting cheaper at a breathtaking speed.
That part of the story is real, and there can be no argument.
But the jump from cheaper digital tasks to a stronger national economy is where much of the faulty thinking starts.
Let me explain.
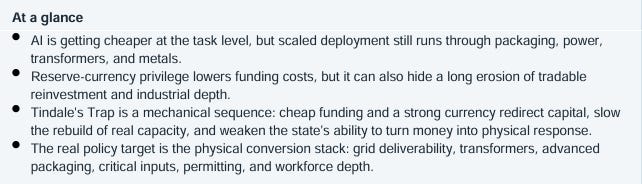
A country can make software more powerful, lower the cost of inference, pour capital into data centers, and still end up more exposed, not less. The reason is simple: AI may be digital at the point of use, but it is physical at the point of scale.
It is a gargantuan industrial metabolism that must be built from toil and matter.
AI can be strongly deflationary at the unit-cost level while the wider system becomes more materially constrained. The collapse in the cost of a fixed level of AI capability maps to physical bottlenecks that shape deployment.
That mismatch is especially dangerous for a reserve-currency issuer such as the United States. Financial ease can hide industrial weakness for years. The physical side of the AI story is what breaks the fantasy.
Large-scale deployment requires accelerators, advanced packaging, high-bandwidth memory, data centers, electricity, interconnection, transformers, copper, water, permits, and labor that can actually connect and operate all of it.
Once usage grows, the relevant price is no longer the token price. It is the price of energized, usable throughput. Digital services can get radically cheaper while the system around them gets harder, slower, and more expensive to expand.
That is the point of this essay.
The question is not whether a country can finance AI. The question is whether it can convert financial and technological advantages into real capacity fast enough.
That is where The Trap starts.
Tindale’s Trap is when a reserve issuer can stay financially powerful while slowly losing the industrial depth, material access, and build speed needed to turn money into real capacity under stress.
It’s essentially a conversion failure between the Financial Ledger and the Material Ledger
What Tindale’s Trap is, mechanically:
Tindale’s Trap is a monetary sequence. The trap appears when a reserve-currency issuer enjoys a real funding advantage, but gradually loses the productive structure needed to make that advantage useful in a crisis.
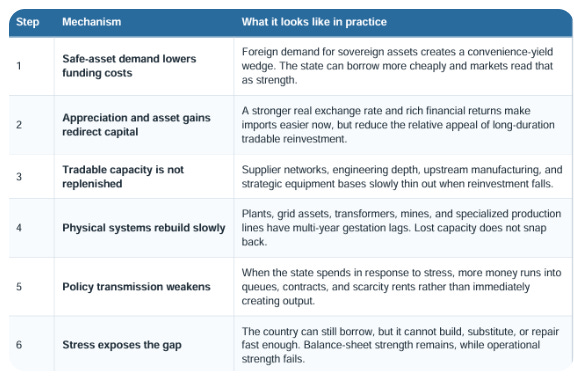
In the model, the danger comes from six coupled steps.
1. Safe-asset demand lowers funding costs. Foreign demand for sovereign assets creates a convenience-yield wedge. The state can borrow more cheaply, and markets read that as a sign of strength.
2. Appreciation and asset gains redirect capital. A stronger real exchange rate and rich financial returns make imports easier now, but reduce the relative appeal of long-duration tradable reinvestment.
3. Tradable capacity is not replenished. Supplier networks, engineering depth, upstream manufacturing, and strategic equipment bases slowly thin out when reinvestment falls.
4. Physical systems rebuild slowly. Plants, grid assets, transformers, mines, and specialised production lines have multi-year gestation lags. Lost capacity does not snap back.
5. Policy transmission weakens. When the state spends in response to stress, more money runs into queues, contracts, and scarcity rents rather than immediately creating output.
6. Stress exposes the gap. The country can still borrow, but it cannot build, substitute, or repair fast enough. Balance-sheet strength remains, while operational strength fails.
The problem starts when policymakers mistake this financial privilege for proof that the productive base is also healthy. Cheap funding is a means, not an end.
Step one is the reserve advantage itself. The model starts with a reserve wedge: an increase in demand for safe sovereign assets pushes funding costs lower than they would otherwise be. That part is not controversial. The problem starts when policymakers mistake this financial privilege for proof that the productive base is also healthy. Cheap funding is a means, not an end.
Step two is capital drift. A strong real exchange rate, easy imports, and rich financial markets change the relative payoff to different kinds of investment. Long-duration tradable reinvestment starts to lose out to faster, more liquid, more obviously rewarded financial uses. The country still looks affluent. In fact, that affluence is what makes the drift easy to miss.
Step three is industrial thinning. If tradable reinvestment stays weak for long enough, the economy does not just lose factories in the crude old sense. It loses upstream suppliers, tooling competence, maintenance depth, power-equipment capability, production know-how, and the web of institutions that let it scale strategically important systems. This is what the paper means by industrial complexity. It is the breadth and depth of capability behind the visible output.
Step four is time. Physical systems have long gestation delays. A transformer factory cannot be rebuilt on a quarter’s notice. A mine does not appear because bond yields are low. Advanced packaging capacity, grid interconnection, substations, and trained installation crews all move on multi-year timelines. That means today’s resilience depends on investment choices made years earlier.
Step five is a weaker conversion efficiency. This is one of the most useful concepts in the paper. Conversion efficiency is the rate at which fiscal space and financial power translate into real throughput. A high-conversion economy can spend and actually get power, equipment, and output. A low-conversion economy can spend and mostly end up with delays, backlog inflation, and bidding wars.
Two countries can have similar access to funding and radically different abilities to turn that funding into a physical response.
Step six is stress activation. In calm times, the system can look fine. Asset prices are high, funding is easy, and shortages are manageable. Then a shock arrives: war, a supply squeeze, an energy crunch, or an AI buildout that suddenly demands far more power and equipment than the system can deliver.
At that point, the trap becomes visible. The state still borrows, but it cannot convert borrowing into capacity at the speed the moment requires.
Three terms in the model deserve plain-English translation because they carry much of the argument.
Tradable reinvestment means the long-horizon investment that renews the country’s ability to make, move, and service goods and strategic equipment. It is not just factory spending in the narrow sense. It includes the supplier base, engineering depth, and industrial services that enable scalable production.
Material sovereignty doesn’t mean trying to make everything at home. It means retaining enough secure access and domestic capability that the loss of one chokepoint does not freeze the whole system.
Conversion efficiency is the bridge between the two. It measures how effectively balance-sheet space is converted into physical output. Once those definitions are clear, the trap becomes easier to see. A country can look richer as a financial center even while those three foundations weaken.
It can own the platforms, write the software, and host the capital markets, yet still struggles to expand power, packaging, grid hardware, and strategic inputs on the timetable that a genuine buildout requires.
That is why the trap is structural.
In AI terms, the trap says this: a country can finance data centers faster than it can energize them. It can subsidize chip demand faster than it can expand packaging or electricity.
It can promise strategic autonomy faster than it can train line crews, install transformers, open mines, or clear permits. Every one of those mismatches is a conversion problem. The balance sheet moves quickly. The physical system can’t.
AI turns the hidden weakness into a visible constraint
AI makes the trap visible because AI is an industrial load, not just a software breakthrough. In the near term, the likely bottlenecks sit in advanced packaging, high-bandwidth memory, and accelerator delivery.
In the medium term, they rotate into grid deliverability, interconnection queues, and transformer backlogs. In the longer term, copper supply and wider fiscal strain become more binding.
The bottleneck moves, but it doesn’t disappear. This rotating structure matters more than any single data point. It means a country does not solve the problem once and then coast it is more likely to be serially constrained.
Each time one layer expands, another layer becomes binding. Cheap model output does not abolish this. It can actually intensify it by making demand for physical deployment rise faster than the supporting systems can respond.
The transformer example is revealing because it exposes the gap between financial commitment and real capacity. A reserve issuer can finance a huge amount of planned AI buildout. It can support high valuations, major private capex, and public subsidies. But none of that compresses transformer procurement and installation from five years into six months.
We currently suffer a multitude of these capacity anchors, gas turbines, critical metal production, skills shortages, and approvals.
None of it produces imported equipment on demand. None of it creates skilled crews by decree. Money matters, but time-to-power is still a physical fact.
Copper tells the same story at a different scale. If new mine and processing capacity takes something like a decade and a half to mature, then medium-term AI expansion is partly constrained by decisions made long before the current boom.
A country that allows upstream capacity to thin out can’t solve
It can pay more for scarce inputs, but paying more is not the same thing as having more. The most important implication is that announced demand is not the same thing as realizable use.
Loads can be over-ordered. Projects can be financed assuming smooth power delivery. Then queues lengthen, equipment slips, utilization disappoints, and the boom starts carrying the seeds of a bust. A thin industrial base hurts twice: first in scarcity and delay, then in the harder downturn that follows when paper buildout proves larger than real buildout.
Rivals interrupt supply.
Why reserve privilege can mislead
Reserve privilege makes this easy to misread. A reserve issuer can remain financially powerful long after its productive structure has thinned out. Sovereign borrowing still looks cheap. Capital markets still look deep. Asset prices can stay elevated.
That is precisely why the trap is plausible. The balance sheet keeps signalling strength while the conversion machinery gets weaker. The macro model captures that with the interaction of industrial complexity, material sovereignty, and conversion efficiency.
Material sovereignty doesn’t mean autarky. It means having sufficient secure access, retained capability, and a substitution room so that a shock does not stop the system cold. In the model, higher material sovereignty carries a calm-state cost. It is not free. But once the stress hazard rises sufficiently, the carrying cost is dominated by lower crisis losses.
Redundancy looks expensive until the system is under pressure. Then it stops looking like redundancy and starts looking like capacity. That is why the policy conversation has to stop treating AI strategy as a software funding problem.
More money aimed at AI, on its own, can simply create more queue inflation, more contract lockups, and more scarcity rents. If the physical conversion stack is weak, extra demand does not produce resilience. It produces heat without enough throughput.
In the balanced case, reserve privilege can coexist with fairly stable industrial depth. If tradable reinvestment is maintained, if supplier networks are replenished, and if strategic capacity is not allowed to decay, then cheap funding is genuinely useful.
The paper doesn’t assert that reserve currency status inherently degrades the industrial base. Instead, it contends that this status profoundly obscures the consequences of capital misallocation. The sudden realization of this reality feels jarring, as the deterioration was allowed to advance unnoticed until reaching a point of systemic failure.
That distinction really, really matters because systems don’t fail in a straight line. The model treats fragility as nonlinear. For long stretches, the country can look manageable. Imports remain available. Funding remains easy. Firms adapt around bottlenecks.
Then enough slack disappears that a fresh surge in demand reveals the system’s true condition. Stress does not create weakness out of nothing. It reveals the weakness that accumulated under apparently favourable financial conditions.
Maintaining more material sovereignty and strategic redundancy costs money in calm times. It can look inefficient next to leaner systems that import more and carry less spare capacity.
This vulnerability was systematically amplified by the FOMC’s policy framework, which structurally selected for such capital misallocation. Constrained by a dual mandate focused on aggregate employment and core inflation, the Federal Reserve persistently relied upon blunt monetary accommodation.
Shielded by the deflationary force of global wage arbitrage, enabled by the dollar’s reserve privilege, the FOMC sustained protracted periods of zero-bound interest rates without triggering traditional inflationary feedback loops.
This artificially suppressed cost of capital distorted risk premiums, generating asymmetric incentives that favored intangible assets and corporate financialization while implicitly penalizing long-horizon, fixed-capital manufacturing.
Consequently, the framework optimized for systemic liquidity on paper while practically engineering the steady atrophy of domestic industrial capacity.
But once stress risk rises above modest levels, the ranking flips. What looked like inefficiency is better modelled as insurance. The country that kept more physical depth suffers smaller losses when the system is tested.
What policy has to stop getting wrong
A serious response starts from a less glamorous place. It has to care about grid deliverability, transformer manufacturing and procurement, advanced packaging, memory-related capacity, copper and critical-input access, permitting throughput, workforce depth, and the tradable reinvestment that keeps industrial capability from thinning further.
Those are not side issues; they are the concrete form of resilience. This is also why the phrase industrial policy is often too vague to be useful. The real issue is not whether the state should support industry in the abstract.
The real issue is whether it can preserve or rebuild the specific layers that determine conversion speed under stress. In the AI buildout, those layers are visible: packaging, memory, substations, transformers, interconnection, transmission, metals, and installation capacity.
The broader implication is uncomfortable because it runs counter to how advanced economies like to see themselves. They often assume that high income, deep capital markets, and technical leadership are enough.
When real national strength is also a question of whether the country still has enough material competence to build the things its strategic position depends on. That is Tindale’s Trap in the age of AI.
The trap is not that the reserve privilege disappears. The trap is that it can survive long enough to hide the erosion beneath it. A country that cannot build, energize, and supply its own systems under stress is not as strong as its balance sheet says it is.
For policymakers, that means the wrong metric is headline AI investment alone.
The right metric is built for speed under stress.
Can the country connect a large new load without multi-year slippage?
Can it source the equipment needed to make that load usable?
Can it substitute when an imported chokepoint tightens?
Can it expand critical inputs without waiting on a distant pipeline set in motion fifteen years ago?
Those are harder questions, but they are the ones that decide whether financial strength becomes real strength. For investors and executives, the lesson is really really blunt.
Cheap intelligence does not mean cheap deployment.
The price that matters at scale is not the model price on a presentation slide.
It is the delivered cost of energized, permitted, connected capacity.
Firms that mistake falling token costs for frictionless scale will overestimate addressable demand, underestimate build delays, and misread where profits will actually concentrate.
The full model will be published in the coming weeks.
Excellent essay. I like the trap model and can see how this has happened in real life.
So is reserve currency status a bad thing on the balance, and therefore should no longer be desired? It is hard to see how the trap can be avoided if the emphasis is on financialization, leverage and consumption - while at the same time abandoning the social contract with its citizens and with mother nature.
Add to this that critical externalities such as human and ecosystem health, extremely rapid depletion of hydrocarbons, development of skills and knowledge, etc., are not accounted for and priced in.
It seems that China is further ahead with its alignment to the material world. Could it be that export of cheap AI tokens is there next big thing?
Thanks for this Craig, in the past, I easily understood that capital was being misdirected, but predicting and benefiting from the denouement is a challenge.